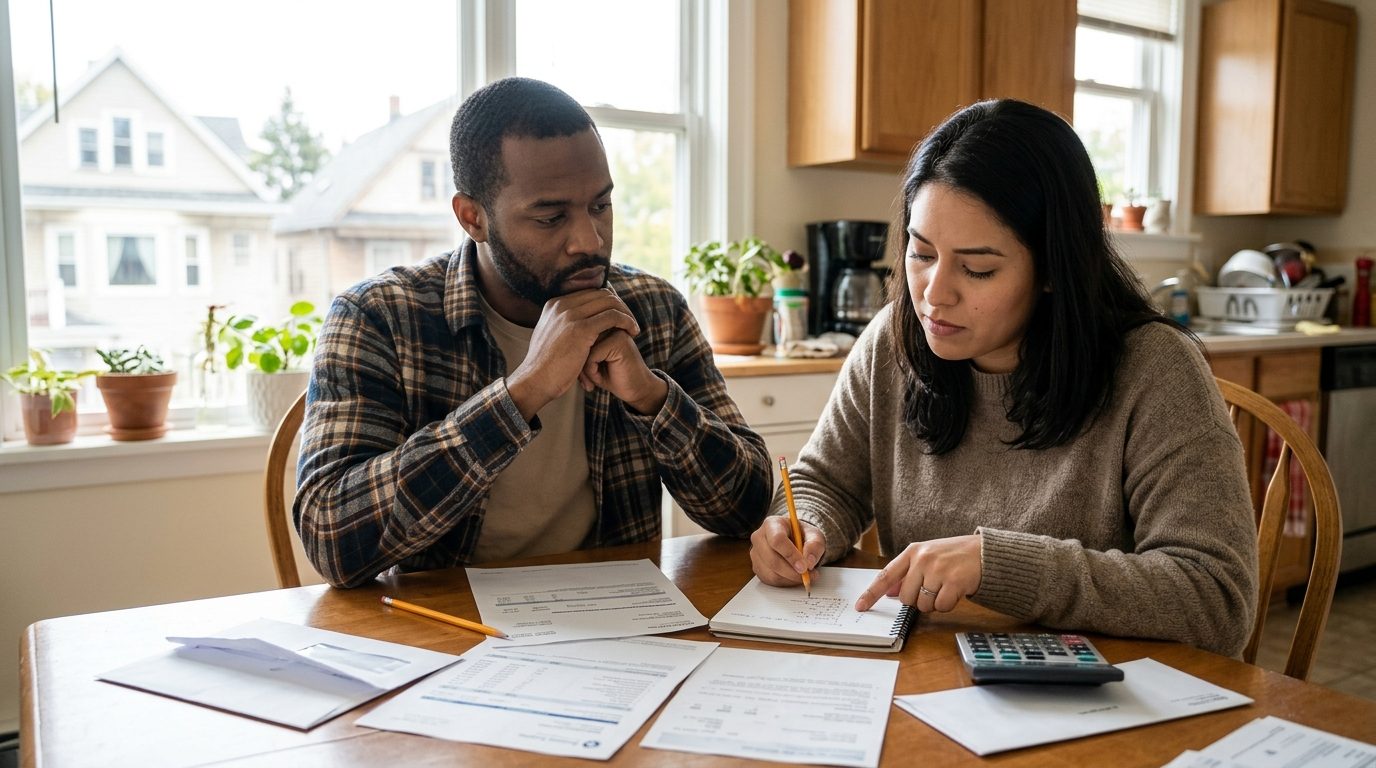
Mariza and Geffrey Gordon are trying to break a costly cycle familiar to many households: living paycheck to paycheck while carrying several debts.
The Milwaukee couple faces little financial room between income, routine expenses and debt payments. Their goal is clear, but reaching it will require careful choices about spending, repayment and emergency savings.
The Gordons’ situation reflects a basic problem with paycheck-to-paycheck living. Even when a household covers its monthly bills, one unexpected expense can force it to borrow again. That can erase progress and extend the repayment period.
Debt Creates Competing Priorities
Managing several debts often means balancing different due dates, interest rates and minimum payments. A household may remain current on every account yet make limited progress on the balances.
For the Gordons, the central challenge is not simply reducing what they owe. They also need enough cash for housing, food, transportation and other required costs. An overly aggressive repayment plan could leave them exposed to the next emergency.
A practical review would begin with a full list of monthly income, essential expenses and debts. Each debt should include its balance, minimum payment and interest rate. That information can show where money is going and which obligations carry the highest cost.
- Protect essential household expenses first.
- Make required minimum payments to avoid added fees.
- Identify spending that can be reduced without disrupting basic needs.
- Choose one clear repayment strategy and track results.
Two Common Repayment Strategies
Households often choose between the debt avalanche and debt snowball methods. The avalanche approach targets the debt with the highest interest rate first. It can reduce total interest costs over time.
The snowball method targets the smallest balance first. Early payoffs may provide motivation and free money for the next debt. However, it can cost more if larger debts carry higher rates.
Neither method removes the need for consistent monthly payments. The better choice depends on the Gordons’ balances, borrowing costs and ability to stay committed.
Debt consolidation may also appear attractive because it can replace several payments with one. Yet a lower monthly bill does not always mean a lower total cost. Fees, longer repayment terms and variable rates can make consolidation more expensive.
Emergency Savings Can Prevent New Borrowing
Debt repayment is only part of breaking the cycle. A small cash reserve can help absorb car repairs, medical costs or changes in income without relying on credit.
That creates a difficult trade-off. Money placed in savings is money not sent to creditors. Still, having no reserve may cause a household to borrow again after an unexpected bill.
The Gordons may need to pursue both goals at once, even if progress begins slowly. A modest automatic savings transfer can build protection while extra available money goes to a selected debt.
Progress Depends on a Sustainable Plan
Any workable budget must reflect the couple’s actual income and required expenses. Severe cuts that cannot last may produce short-term gains, followed by renewed borrowing.
Outside guidance may help, but the source matters. Reputable nonprofit credit counselors can review budgets and repayment options. The couple should closely examine fees and avoid firms that promise quick debt removal or advise stopping creditor payments.
For Mariza and Geffrey Gordon, the next step is turning a broad goal into a measured plan. Tracking balances, creating a small reserve and directing extra cash consistently could begin to reduce their financial pressure.
The larger test will be whether that plan remains workable through unexpected expenses. Their experience shows that leaving paycheck-to-paycheck life requires more than paying debt. It also requires enough financial space to avoid taking on new debt when the next bill arrives.

A seasoned technology executive with a proven record of developing and executing innovative strategies to scale high-growth SaaS platforms and enterprise solutions. As a hands-on CTO and systems architect, he combines technical excellence with visionary leadership to drive organizational success.